If you have heard the terms income statement, profit and loss statement, and P&L used interchangeably, there is a simple reason. In most business accounting contexts, they refer to the same financial report.
The terminology may vary between accountants, software platforms, and reporting systems. What matters is understanding what the report tells you about revenue, expenses, and profitability.
An income statement and a profit and loss statement are generally the same report. Both show how much your business earned, what it spent, and whether it generated a profit or loss over a specific period.
Are Income Statements and Profit and Loss Statements the Same?
In most cases, yes.
When comparing an income statement vs profit and loss statement, the main difference is terminology rather than the financial information each report provides.
The term income statement is common in formal accounting and financial reporting. Small business owners, bookkeepers, and accounting software often use profit and loss statement or P&L statement instead.
You may also see QuickBooks reporting refer to a P&L while your accountant calls the same report an income statement.
Regardless of the name, both reports help you evaluate business performance over a specific period.
What Does an Income Statement or P&L Show?
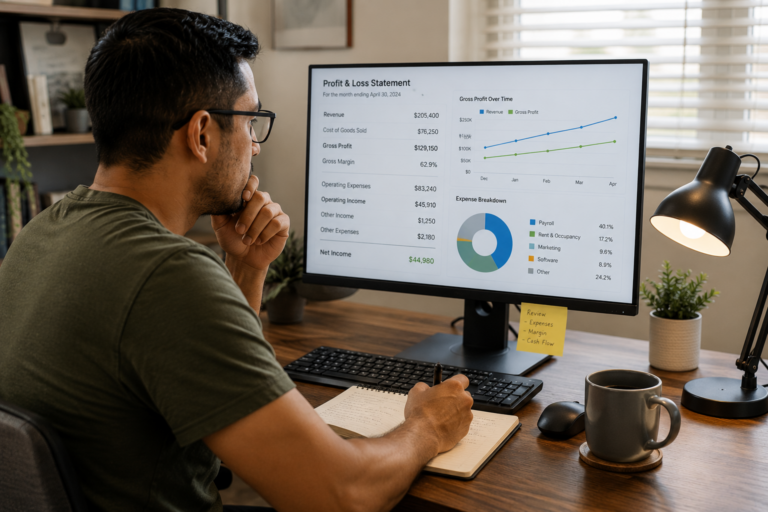
Understanding the income statement meaning starts with knowing what appears on the report.
Your exact format depends on your business and chart of accounts, but most income statements include:
- Revenue: Income your business earns from selling products or services.
- Cost of goods sold: Direct costs associated with producing or delivering what your business sells.
- Gross profit: Revenue remaining after subtracting cost of goods sold.
- Operating expenses: Costs of running the business, such as payroll, rent, software, marketing, and insurance.
- Operating income: Profit remaining after operating expenses are deducted from gross profit.
- Net income: The final profit or loss after applicable expenses are deducted from revenue.
Together, these numbers show whether your business generated a profit or loss during the reporting period.
Monthly financial statements also make it easier to compare results over time rather than evaluating one month in isolation.
How Should Business Owners Use a P&L?
A P&L becomes more useful when you move beyond simply checking revenue or net income.
Reviewing the report consistently can help you:
- Track profitability: See whether the business generates a profit and how that changes over time.
- Monitor expenses: Identify costs that are increasing faster than expected.
- Understand margins: See how much revenue remains after direct costs and operating expenses.
- Compare performance: Review monthly, quarterly, or yearly results for meaningful trends.
- Support business decision-making: Use current financial data when evaluating pricing, hiring, or spending.
Financial analysis often starts with asking why a number changed.
For example, revenue may increase while net income decreases. Reviewing cost of goods sold, payroll, or other expenses can help explain what changed and where you may need to look more closely.
Income Statement vs Balance Sheet vs Cash Flow Statement
Your income statement is important, but it does not provide a complete picture of your finances.
Three key financial statements serve different purposes:
- Income statement or P&L: Shows revenue, expenses, and profit or loss over a period.
- Balance sheet: Shows what your business owns and owes at a specific point in time.
- Cash flow statement: Shows how cash moves into and out of the business.
Looking at these reports together provides stronger financial visibility.
This distinction also helps prevent a common mistake: confusing profit with cash. A profitable business can still experience cash flow challenges because net income and available cash measure different aspects of the business.
Avoid These Common P&L Mistakes
A P&L statement is only useful when you understand the numbers and can trust the data behind them.
Common mistakes include focusing only on revenue, ignoring gross profit, overlooking changes in expenses, confusing profit with cash flow, and failing to compare performance across periods.
Another major issue is relying on outdated or inaccurate bookkeeping. Even a well-formatted income statement can misrepresent business performance when the underlying financial records contain errors.
Accurate Bookkeeping Creates More Useful Financial Reports
Reliable financial reporting starts with accurate bookkeeping.
Transactions need correct categories, bank accounts need regular reconciliation, and your chart of accounts should organize financial activity in a meaningful way. These processes help ensure that the numbers flowing into your income statement accurately reflect your business activity.
As your business grows, you may decide to Hire a Bookkeeper or use Virtual Bookkeepers to maintain those records. Businesses that prefer external support can also use Outsourced Bookkeeping Services for ongoing financial recordkeeping.
Accurate books do more than produce cleaner reports. They give you financial information you can actually use.
How Rise CPA & Accountants Helps You Understand Your Numbers
At Rise CPA & Accountants, we help business owners move beyond simply receiving financial statements.
Our bookkeeping, accounting, and reporting support helps organize financial records and provides clearer insight into revenue, expenses, cash flow, and profitability.
The goal is not just another report. It is financial information that helps you understand how your business is performing and supports more informed decisions.
Ready to Make More Sense of Your Numbers?
Financial reports should give you answers, not leave you wondering what the numbers actually mean.
Rise CPA & Accountants can help you keep your financial information accurate, understand what your reports are telling you, and use those insights to make more informed business decisions.